Veru Inc. ($VERU) – The Path to a 10× Return


 RSS Feed
💡 Welcome to Make Money, part of the Finance Frontier AI podcast network — where we analyze asymmetric opportunities through survival, validation, scalability, and repricing.
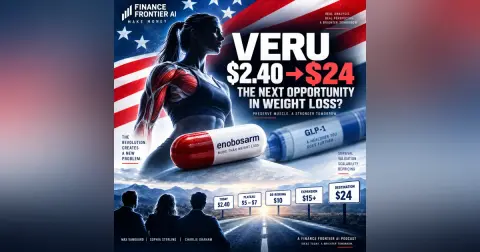
In this episode, Max Vanguard, Sophia Sterling, and Charlie Graham examine Veru Inc. ($VERU), a clinical-stage biotech developing enobosarm to potentially preserve muscle during GLP 1 weight loss.
This is not a stock pitch. It is a documented case study in asymmetric investing — and in finding the problem created by the revolution.
🔹 Snapshot Date — September 19, 2026.
🔹 Current Price — ~$2.40.
🔹 Market Cap — ~$40 million.
🔹 1-Year Target — $10 (≈4×).
🔹 5-Year Target — $24 (≈10×).
🔹 Starting Allocation — 0.5%.
🔹 Risk/Reward — ~7:1 under the base downside assumption.
🔹 Lead Program — Enobosarm for muscle preservation during GLP 1 treatment.
🔹 Clinical Status — PLATEAU Phase 2b fully enrolled with 239 patients.
🔹 Next Major Gate — PLATEAU interim analysis expected Q1 2027.
📊 The Core Question
What would have to be true for a ~$2.40 clinical-stage biotech stock to reach ~$24 over the next five years?
We evaluate VERU through four gates:
✅ Survival
✅ Validation
✅ Scalability
✅ Repricing
If the clinical thesis fails, the path can break quickly. If the evidence strengthens, safety holds, financing remains manageable, and enobosarm becomes a meaningful obesity asset, Veru could be valued very differently.
🧱 What You'll Learn
• How the GLP 1 revolution may create a second-order opportunity around muscle preservation.
• What Veru's QUALITY study showed — and what it did not prove.
• Why the 239-patient PLATEAU study is the next major validation gate.
• Why competition validates the category while raising the bar for Veru.
• What the Novo Nordisk relationship does — and does not — mean.
• Why cash runway and dilution can destroy returns even if the science works.
• How the conditional path could move from ~$2.40 to $5–$7, $10, $15+, and ultimately $24.
• Why position size should increase with evidence, not excitement.
⚠️ Key Risks
Clinical failure. Safety. Financing. Dilution. Competition. Regulatory uncertainty. Timeline delays. Permanent capital loss.
📝 Documentation, Not Prediction
This episode documents the VERU thesis as of September 19, 2026.
The starting price, targets, risks, and gates are recorded before the outcome is known.
Five years from now, reality will provide the scorecard.
VERU may never reach $24. Or enobosarm may become a meaningful solution to a problem created by one of the biggest drug revolutions in modern medicine.
Today we do not know the outcome. We only know the path.
🌐 Explore More
📢 Visit FinanceFrontierAI.com and explore Make Money.
📲 Follow us on X for asymmetric opportunities and structural analysis.
📬 Submit your pitch here.
Keywords: Veru, VERU stock, enobosarm, GLP 1, muscle preservation, lean mass, obesity treatment, Wegovy, semaglutide, Novo Nordisk, PLATEAU trial, QUALITY trial, biotech investing, microcap stocks, asymmetric investing, 10x stocks, obesity stocks, dilution risk, position sizing, Finance Frontier AI, Make Money podcast.
Topics Covered: Veru Inc. (NASDAQ:VERU), enobosarm, GLP 1 weight loss, muscle preservation, QUALITY, PLATEAU Phase 2b, Novo Nordisk, biotech valuation, cash runway, dilution, clinical risk, competition, asymmetric risk-reward, position sizing, and second-order investment opportunities.


